For many Non-Resident Indians (NRIs), tax is no longer a once-a-year India filing exercise. A UK-based professional with Indian rent, NRE/NRO accounts, mutual funds, dividends or property gains may have reporting obligations in both India and the country where they live. The result is a cross-border tax puzzle: two tax years, two residency tests, different income classifications, and one big risk - missing a disclosure that later triggers interest, penalties or notices.
This 2026 NRI tax guide explains what cross-border tax means, why India-UK tax filing can get complicated, and how NRIs can stay organised with a practical annual checklist for residency, income reporting, TDS, DTAA relief and refund claims.
1. What is Cross-Border Tax for NRIs?
Cross-border tax is the process of managing income, assets, deductions, withholding tax and reporting across more than one country. For NRIs, it usually starts with one question: where am I tax resident this year?
India taxes a non-resident mainly on India-sourced income such as Indian rent, NRO interest, dividends and capital gains. A Resident and Ordinarily Resident may be taxed on worldwide income, while Resident but Not Ordinarily Resident (RNOR) status can provide a transition window where most foreign income remains outside the Indian tax net. In 2026, the key Indian day-count rules still matter: broadly, 182 days in India can make you resident; for certain visiting Indian citizens or persons of Indian origin with Indian-source income above ₹15 lakh, a 120-day threshold can apply when other conditions are met.
Your country of residence may tax differently. For example, UK tax rules may require reporting foreign income, so income that is tax-free in India - such as NRE interest - may still need to be reported in the UK. Double Taxation Avoidance Agreements (DTAAs) help prevent the same income being taxed twice, but they do not remove the need to file correctly in both places.
2. India-UK Tax Filing Complexities for NRIs
India and the UK do not use identical tax years. India follows 1 April to 31 March, while the UK tax year runs from 6 April to 5 April. That small mismatch can create apportionment work for salary, bonuses, investment income and capital gains. Add separate residency tests, exchange-rate conversion, foreign tax credit claims and different deadlines, and the compliance burden quickly grows.
Common India-UK examples include:
- Indian rental income reported in India but also disclosed in the UK
- NRO interest with Indian tax deducted at source
- Indian mutual fund gains taxed under Indian capital-gains rules and then considered again in the UK
- Pensions and dividends where treaty treatment must be checked
The DTAA can cap withholding tax on certain income streams and allow credit relief, but the paperwork - Tax Residency Certificate, treaty forms, foreign tax credit schedules and supporting statements - must be consistent. In India, non-residents claiming treaty relief may also need supporting forms such as Form 41, depending on the applicable law and fact pattern.
3. Annual NRI Tax Checklist for 2026
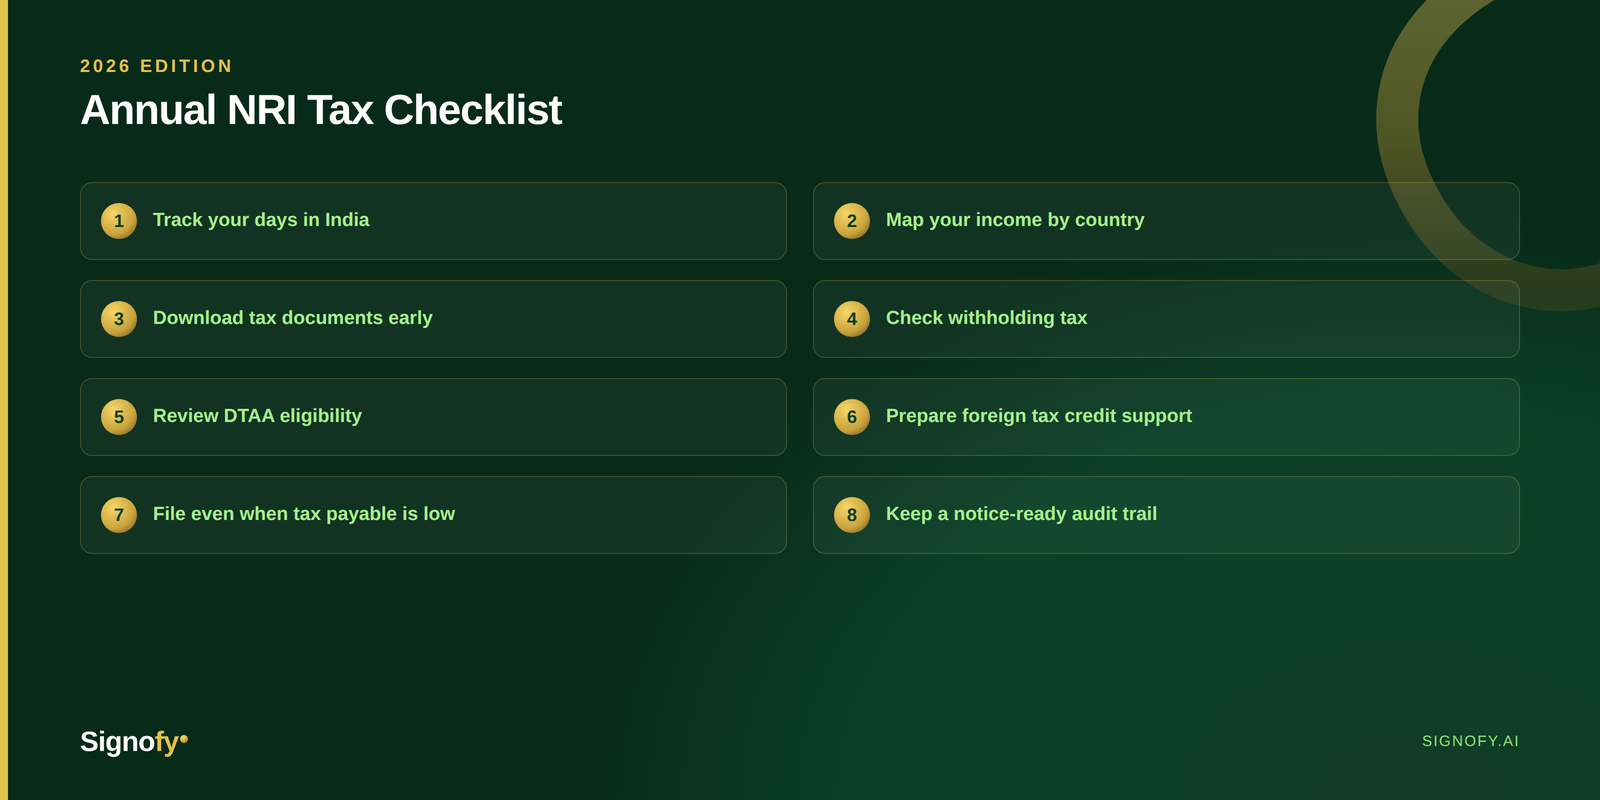
- Track your days in India. Count by the Indian tax year, including arrival and departure days. Review whether you are NRI, RNOR or resident.
- Map your income by country. Separate Indian rent, NRO/NRE interest, dividends, capital gains, salary, pensions and overseas investment income.
- Download tax documents early. Collect Form 26AS, AIS/TIS, bank interest certificates, capital-gains statements, rent records, TDS certificates and broker reports.
- Check withholding tax. Confirm whether Indian TDS has been deducted correctly on rent, property sale, NRO interest, dividends or mutual fund transactions.
- Review DTAA eligibility. Keep your Tax Residency Certificate, treaty declaration and required Indian forms ready before claiming lower withholding or relief.
- Prepare foreign tax credit support. Match income, taxes paid, dates and currency conversions so credits claimed in one country reconcile with filings in the other.
- File even when tax payable is low. If excess TDS has been deducted in India, filing an ITR may be necessary to claim a refund.
- Keep a notice-ready audit trail. Preserve lease agreements, remittance records, bank statements, broker notes and tax computations for future queries.
4. NRI Tax Traps and Loopholes to Avoid
NRI does not mean no Indian tax. Indian rent, NRO interest, dividends and capital gains can still be taxable in India. Assuming otherwise is one of the fastest routes to notices.
NRE interest is not always globally tax-free. It may be exempt in India, but countries such as the UK may tax it if you are resident there.
Rent paid to an NRI landlord can trigger heavy tenant compliance. Rent to a non-resident landlord is generally covered by Section 195 withholding rules, not the familiar resident-landlord TDS rules. Tenants may need to deduct around 31.2% TDS, obtain a TAN and complete quarterly reporting unless a lower-deduction certificate or treaty position applies.
DTAA relief is not automatic. Treaty benefits usually need evidence - such as a Tax Residency Certificate and the right forms. If documents are missing or inconsistent, a lower rate may be denied.
Mutual fund tax treatment can surprise NRIs. Equity long-term capital gains, short-term gains and debt-fund taxation do not follow the same logic. Gains may also be reportable where you live, creating foreign tax credit and timing issues.
5. How Signofy Helps NRIs Manage Cross-Border Tax
Signofy is a purpose-built cross-border tax platform for NRIs and expats managing taxes across more than one country. Instead of leaving users to coordinate spreadsheets, scattered bank statements and country-specific filing calendars, Signofy helps bring the tax picture together in one workflow.
For an NRI with India and UK obligations, Signofy can support annual tax readiness by helping organise income sources, track documents, surface country-specific compliance tasks, and prepare information needed by tax professionals. The goal is simple: fewer missed disclosures, cleaner records, better visibility into TDS and refunds, and less panic when filing season arrives.
Conclusion
Cross-border tax is not just about paying tax twice or avoiding tax twice. It is about proving, every year, which country can tax which income, how much tax has already been withheld, and what relief you are entitled to claim. For NRIs - especially those balancing India and the UK - the safest approach is to track residency, document income, file on time and keep evidence ready. With the right annual process and tools like Signofy, cross-border tax can move from a stressful surprise to a managed routine.
Ready to simplify NRI tax compliance?
Join your peers already on the waitlist for AI-native cross-border tax management.
Get Free Lifetime AccessTax rules and their application can change. Review current HMRC guidance and obtain professional advice for complex or high-value matters.